#cannabisaficionado

Cannabis

Fine Fettle’s North Haven Opening Adds a New Stop for Connecticut Shoppers

Fine Fettle announced an October 23 opening in North Haven, with a separate celebration October 30. Here is the retail, ownership and consumer context.

Published

on

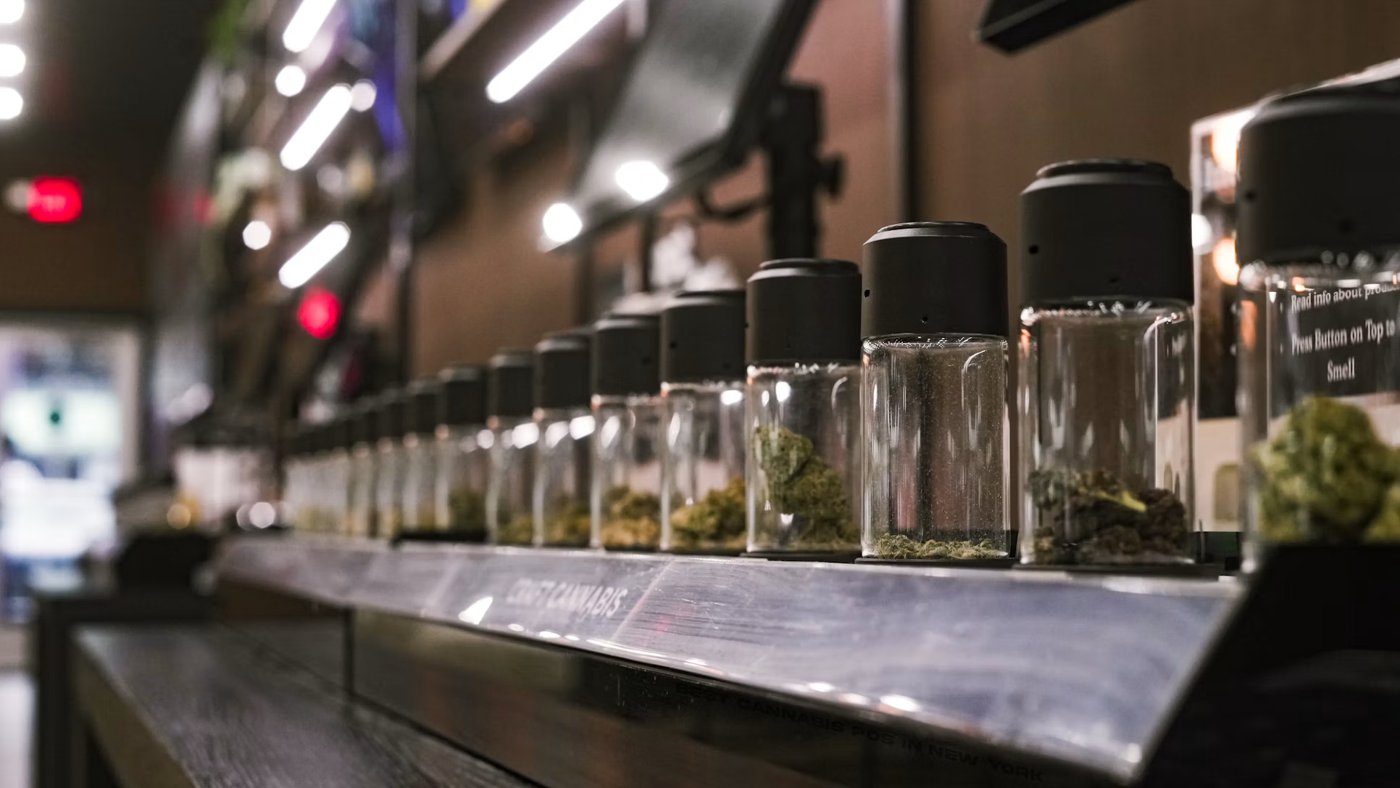
Glass display jars containing cannabis flower in a retail setting
Advertisement Back2Grow Advertisement

Fine Fettle has announced an October 23 opening for its North Haven dispensary, adding another adult-use shopping option in Connecticut’s New Haven County. The new location at 104 Washington Avenue is the company’s tenth retail store in the state, according to its October 22 announcement.

There are two dates to keep separate. The company set the start of business for October 23 at 9 a.m.; its ribbon-cutting celebration is planned for October 30 at 11 a.m. A shopper looking for the opening-day event could otherwise arrive a week earlier than intended.

A new address within a larger Connecticut footprint

The company announcement, also published by Cannabis Business Times, describes the site as an adult-use recreational dispensary. Listed hours are 9 a.m. to 9 p.m. Monday through Saturday and 10 a.m. to 6 p.m. Sunday. The October 30 program is expected to include vendor appearances and merchandise giveaways.

Those details establish what the operator has announced, rather than an independent review of the store. Cannabis Aficionado has not visited, assessed the selection or tested products sold there. Readers can use the North Haven location page to check current store information before making a trip.

For a customer, an additional location can change the practical shopping calculation: travel time, opening hours and the ability to ask questions in person. It does not automatically establish lower prices or a wider selection. Those are comparisons to make against the actual menu and final checkout total, rather than assume from a company’s expanding store count.

Adult-use retail is a specific designation

Connecticut maintains separate medical and adult-use cannabis programs. Its official program comparison explains that adult-use purchasing is available to adults 21 and older without medical-program registration. Medical purchasing instead involves practitioner certification and registration as a qualifying patient or caregiver.

That distinction matters when reading an opening announcement. A company may operate several types of stores, and a familiar brand name does not establish that every location offers the same medical services. North Haven is described in this announcement as adult-use; patients should verify the particular services and transaction category they need.

The state also distinguishes the tax treatment of the two markets: adult-use purchases carry taxes, while qualifying medical medication is nontaxable. Comparing an advertised retail price with a medical purchase therefore requires attention to what is included. A shelf price and an out-the-door total are different pieces of information.

The state’s comparison currently lists a 6.35 percent sales tax, a 3 percent municipal tax and a 10.75 percent flat cannabis tax for adult-use purchases. Those published rates help explain why customers should compare the final transaction category as well as the product.

None of that makes retail guidance a substitute for medical care. A staff member can explain the products on a menu; individual treatment decisions involve a different relationship and a different set of questions.

What the equity venture description means

Fine Fettle identifies North Haven as its seventh equity joint venture. That is a description of the company’s network, not a claim that the state allows one licensed sponsoring establishment an unlimited number of such partnerships.

Connecticut’s equity joint venture guidance describes a structure involving eligible participants with at least 50 percent ownership and control, in partnership with a licensed operator. Its guidance separately addresses limits on sponsoring establishments and the licensing requirements that ventures must satisfy.

The useful point for readers is that equity is about ownership and control, not simply a name on the storefront or a charitable contribution. Fine Fettle’s release does not provide the North Haven partnership’s complete operating agreement, financing terms or division of day-to-day responsibilities. The announced structure should not be mistaken for an independent assessment of those arrangements.

As the business operates, meaningful questions include whether ownership produces decision-making power and whether the venture can sustain itself. A ribbon cutting records a beginning. It cannot demonstrate the long-term outcomes of a licensing policy.

What shoppers can evaluate after the opening

A new store becomes more informative once there is a record of how it serves its market. Useful comparisons include product availability, transparent pricing and whether staff can explain labels and formats without promising an experience that every customer will share.

Our coverage of Bountiful Farms’ reported retail growth in Massachusetts offers a related reminder: store counts, customer counts and revenue answer different questions. An opening expands a company’s footprint; it does not, by itself, establish market share or customer satisfaction.

For now, the concrete North Haven news is the announced retail start and the separate October 30 celebration. The next chapter is what customers and the community experience after the doors open.

Illustrative dispensary stock photograph; not a Fine Fettle location or its product selection. Photo: Cova Software / Unsplash.

Cannabis

North Carolina’s Cannabis Debate Turns to Who Would Run the Stores

A discussion draft separates private cannabis production from state-controlled retail. The council’s work remains advisory, with major design choices unresolved.

Published

on

North Carolina Legislative Building in Raleigh with American and state flags

North Carolina’s cannabis policy discussion is moving beyond a yes-or-no argument about legalization to a more practical question: if the state creates a regulated market, who would run it? A licensing discussion draft posted by the governor’s advisory council explores private production paired with state-controlled retail, with a separate pathway for smaller farms.

The distinction is consequential for shoppers and businesses alike. A system can permit adult access while making very different choices about storefront ownership, product distribution and the opportunities available to growers. The document describes options for discussion; it does not create licenses or authorize new stores.

A proposal on the council’s public record

The North Carolina Advisory Council on Cannabis website lists a Market and Regulatory Subcommittee meeting for October 23, alongside further council and subcommittee meetings later in the month. Its materials include a licensing draft associated with the September 18 meeting.

A calendar entry is not a record of a vote. At the time of this review, the posted material establishes the proposal available for discussion, not an adopted October 23 outcome. Readers following the debate should look for subsequent minutes, revised drafts or a final recommendation before treating any option as settled.

Recent reporting by Tony Lange at Cannabis Business Times placed the council’s market-design work within the broader reform debate. The underlying documents are particularly useful because they show how much remains to be decided beneath a general promise of regulation.

Separate the grower, distributor and retailer

The two-page licensing discussion draft outlines three functions: producing, distributing and retailing. Private licensed businesses would cultivate and manufacture, while the retail channel would remain under state control. It draws on North Carolina’s alcohol-control structure and Québec’s cannabis retail approach.

The draft also considers different distribution arrangements, including independent private wholesalers, a state warehouse or a combination. Retail organization has alternatives too: a centralized state system or a decentralized structure involving local boards.

For readers, the important distinction is between controlling the sales channel and operating every part of the supply chain. A government-controlled storefront model need not mean government-grown flower. Likewise, separating production and retail does not settle how products would be selected, priced or made available in different communities.

Those choices deserve separate scrutiny. A retailer’s ownership tells a shopper one thing; the range of producers represented on its shelves tells another. The eventual rules would need to explain how those interests meet.

A craft-farm pathway is part of the discussion

The proposal includes a small-scale craft-farm license alongside standard cultivation and manufacturing categories. It also raises questions about preventing vertical integration and about what forms of common ownership should be prohibited. These remain design questions, not application instructions.

For a smaller grower, a named license category is only a starting point. Practical access would also depend on costs, production allowances and the ability to reach buyers. A future framework could look welcoming on paper while leaving important details unresolved; evaluating it requires reading those details together.

Our reporting on New York’s cannabis nursery application window covers a different part of the same wider issue: rules for supplying the plant can shape a market well before a retail transaction occurs. The two states’ proposals and permissions should not be treated as interchangeable.

Why the council is examining the existing market

The council’s April 2 interim report frames the problem as how to bring an already-existing intoxicating cannabis marketplace under meaningful oversight. It identifies inconsistencies in testing, labeling, packaging and age verification as central concerns.

The report also distinguishes regulation based on the plant’s legal classification from an approach focused on intoxicating cannabinoids. That is a policy argument about consistent oversight, rather than a claim that every product has identical effects or risks.

The report explicitly describes the council as advisory and places authority for changing the state’s framework with the General Assembly. A recommendation, even a detailed one, is therefore a different event from legislation becoming law.

The next documents matter more than predictions

Executive Order No. 16, which established the council in June 2025, calls for final recommendations by December 31, 2026. Its duties extend beyond retail structure to youth protection, public health, impaired driving, justice and administration.

That wider remit is a useful test for the final package. Watch how a proposed sales model connects with product standards, enforcement resources and opportunities for smaller businesses. A credible framework needs those pieces to work together.

North Carolina has a public set of questions about what regulated cannabis could look like. The news to watch next is which answers the council recommends and which, if any, lawmakers turn into enforceable rules.

North Carolina Legislative Building in Raleigh. Archival stock photograph; not a photograph of the advisory council meeting. Photo: Elijah Mears / Unsplash.

Continue Reading

Cannabis

DEA Judge Keeps Cannabis Hearing Closed but Adds a New Briefing Round

An October 22 order admits a GAO report and sets briefing deadlines while rejecting new testimony. It does not resolve the broader rescheduling proposal.

Published

on

United States Capitol building with its dome and columns beneath a blue sky

The judge overseeing the broader federal cannabis rescheduling proceeding has rejected a request to reopen the hearing for new testimony, while allowing another round of written arguments. The October 22 order keeps the dispute over a recent government oversight report inside the existing administrative case.

That is a procedural development, rather than a final answer about cannabis scheduling. For readers following the long-running debate, the useful change is a defined set of briefing deadlines and a narrower account of what the parties can argue next.

A closed hearing and an open written record

Chief Administrative Law Judge Derek C. Julius issued the five-page order after opposing parties sought to add a Government Accountability Office report and pursue further discovery and testimony. The hearing on the merits had run from June 29 through July 15.

The judge admitted the report and permitted limited written briefs. Initial submissions are due October 29, with replies due November 5. The order says the matter remains stayed until the briefing period closes, with the stay expiring under that schedule.

Those dates are filing deadlines. They are not promised dates for a final federal rule, a change at a dispensary or a particular outcome. Treating a procedural calendar as an implementation calendar can make an already complicated process harder to follow.

Reporting by Tony Lange at Cannabis Business Times highlighted the split result: additional legal argument is allowed, but the requested reopening of the hearing is not.

What the government oversight report examined

The GAO report, released September 23, examined federal drug-scheduling procedures across substances. Its concerns included incomplete written policies identifying responsibilities and evaluation procedures, plus an outdated agreement governing consultation between agencies.

GAO recommended improvements by DEA, FDA and NIH, and reported that the agencies agreed with its recommendations. It also found that, among the reviewed substances for which final rules had been published and HHS recommendations were required, DEA’s decisions aligned with those recommendations.

That combination matters. A call for better procedural documentation is not the same thing as a finding that every underlying scientific assessment is wrong. Nor does historical agreement prove that a particular future recommendation must prevail. The report and the cannabis case ask related but distinct questions.

For a reader, the safest comparison is to keep the subject of each document visible: the oversight report evaluates agency processes; the administrative proceeding considers a specific proposed scheduling action.

Admission does not decide persuasive weight

Putting a document in the record makes it available for consideration. It does not dictate how persuasive the judge must find it. The remaining argument concerns whether the oversight findings meaningfully affect this particular proceeding.

That distinction explains why the two parts of the ruling can coexist. A tribunal can accept a document without agreeing that it justifies repeating a hearing. It can also invite argument about significance without accepting the outcome any participant prefers.

The question for the next filings is therefore more specific than whether someone supports or opposes cannabis reform. Watch whether an argument connects an identified procedural concern to the actual record and decision before the judge, rather than simply repeating a broader position about the plant.

The broader case is separate from April’s narrower action

Federal cannabis developments this year have not all covered the same products. In its April announcement, the Justice Department described placing FDA-approved marijuana products and products regulated by qualifying state medical marijuana licenses in Schedule III, while initiating a hearing process on broader rescheduling.

Conflating those actions can produce misleading headlines in either direction. The October procedural order does not announce that every cannabis product has moved into a new schedule. It also should not be read as erasing the separately announced medical action.

State licensing remains another distinct layer. Our coverage of Kentucky’s expanding medical cannabis retail network concerns access under a state program, rather than a ruling in this federal case. A development in one system does not automatically explain every requirement in the other.

What to watch after the filings

The immediate milestones are the October 29 briefs and November 5 replies. The next meaningful update will be what the tribunal does with the completed record, rather than speculation that a deadline guarantees a particular result.

For consumers, patients and businesses, the order offers a clearer procedural map. It closes one requested route back into testimony while leaving a defined opportunity for written argument. The ultimate scheduling decision remains a separate step, and its timing should be reported when there is an authoritative action to report.

The U.S. Capitol in Washington, D.C. Illustrative federal-policy stock photograph; the DEA administrative hearing is a separate proceeding. Photo: Tim Mossholder / Unsplash.

Continue Reading

Cannabis

Missouri’s 93% Cannabis Market Share Comes With Important Fine Print

A state-funded study finds strong participation in Missouri’s licensed cannabis market. Its spending estimate, sample and ownership limits deserve a closer look.

Published

on

Point-of-sale screen on a cannabis dispensary counter with people in the background

Missouri’s licensed cannabis market appears to be winning a large share of consumer spending. The more useful story is what that success looks like when the headline number is unpacked: who was surveyed, what they bought, and which questions the research did not attempt to settle.

In its October 15 announcement, the Missouri Division of Cannabis Regulation described a relatively stable market and said the findings did not establish a present need for additional licenses. The agency also committed to continued monitoring, including a closer look at ownership in future research. That makes this a snapshot for regulatory decisions, rather than a permanent verdict on how many stores the state should have.

Spending share is not the same as every transaction

The Phase 1 Missouri Cannabis Market Study, prepared by Cannabis Public Policy Consulting, estimates that licensed stores and delivery accounted for approximately 93% of reported cannabis expenditures among past-month consumers. The word “reported” matters. This is an estimate drawn from consumer research and checked against administrative data, not a direct census of every legal and illegal purchase.

The study’s survey fieldwork ran from March 16 through April 3, 2026. It began with 1,200 adults who had used cannabis in the previous 30 days; the cleaned analytic sample included 1,033 respondents. An October publication date does not turn those responses into an October shopping survey. Readers should keep the observation period separate from the release date when comparing this result with newer developments.

There is another distinction: spending is measured in dollars. It is not interchangeable with the share of people who ever use a licensed store, the number of purchases they make, or the physical amount of cannabis they obtain. A shopper can use several sources. A product can also be purchased legally and later shared without another retail sale. Those possibilities are why a market-share claim needs a clearly named denominator.

Flower still anchors the shopping basket

MJBizDaily’s October 20 coverage highlighted the study’s consumer-facing findings: flower represented roughly half of reported monthly spending, with vapes and edibles following. Average monthly spending across sources was $161.81. Price, THC potency and convenience were important purchasing considerations.

That average is a description of the surveyed market, not a recommended cannabis budget. Nor does a preference for potency establish that a higher-THC product is better suited to an individual consumer. For enthusiasts, the findings are most useful as a picture of the formats and practical shopping considerations shaping retail demand.

A statewide average can also conceal different experiences. Someone close to several stores may have a very different view of convenience from someone planning a longer trip. The question for a local market is not simply whether legal spending is high in aggregate, but whether the available stores, formats and prices work for the people using them.

Store competition and company ownership are different questions

The state’s announcement said sales were not excessively concentrated among retail locations. It also explicitly acknowledged that the study did not include every factor relevant to evaluating a market, including ownership data. Several storefronts can operate under common ownership, so a count of competing locations is not automatically a count of independent businesses.

That is a useful limitation to carry into the licensing debate. Evidence that sales are distributed across facilities can inform one question. It cannot, by itself, establish how much corporate control exists behind those facilities. Future ownership analysis could add a different layer without invalidating the location-level findings.

The regulator said its assessment will also account for ongoing state and federal changes and the forthcoming rollout of additional microbusiness licenses. The immediate message is continued observation, not a promise that today’s licensing structure will remain fixed.

Access is more than an overall percentage

A high licensed spending share and a remaining access problem can coexist. The people already buying cannabis are the population measured here; their behavior does not establish that every potential consumer finds a suitable store. That distinction is especially relevant when officials consider new entrants. Evidence about current demand should sit alongside questions about local access, ownership and the opportunities available to smaller businesses. A strong statewide result is a reason to study those questions carefully, rather than assume they have disappeared.

What deserves attention next

The agency described this as the first phase of a two-part project, with a broader economic-impact report planned for later in 2026. That next phase should be read as new work with its own scope, rather than assumed to be contained in the current market-share figure.

For now, Missouri offers evidence of strong participation in licensed sales, along with a reminder to read market research precisely. Ask when the data were collected, whether a percentage represents dollars or units, and whether competition is measured by stores or owners. Those details turn a striking statistic into information that can actually help explain a cannabis market.

Related reading: Kentucky’s expanding medical cannabis retail network.

Illustrative stock photograph of a dispensary counter; not a documented Missouri retailer. Photo: Cova Software / Unsplash.

Continue Reading

Trending

Join The Cannabis Aficionado Community!
Join the Cannabis Aficionado community and receive all of the most relevant news geared towards our sophisticated enthusiast community.
Loading

Copyright ©️ 2026 Cannabis Aficionado. Cannabis Aficionado is a registered trademark of CNM Inc. All rights reserved. Registration on or use of this site constitutes acceptance of our Terms of Service, Privacy Policy and Cookies Policy. People may receive compensation for some links to products and services. Offers may be subject to change without notice.