#cannabisaficionado

Cannabis

Canada’s Cannabis Sales Hit a New High, but the Details Matter

New August figures point to a Canadian retail record. Revisions, regional differences and separate product data put the headline in perspective.

Published

on

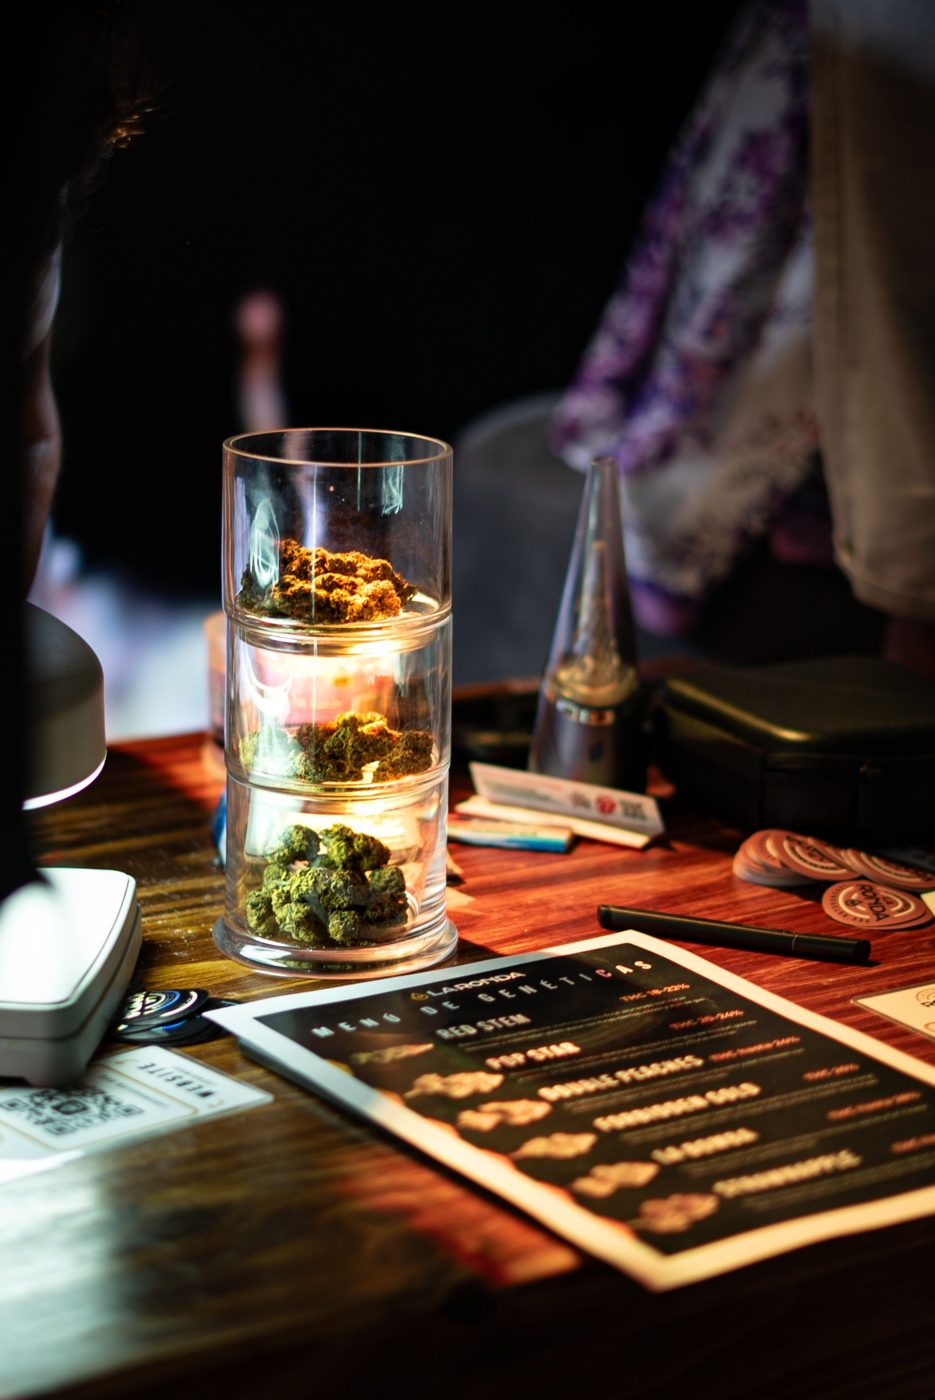
Cannabis flower in glass display jars on a dispensary counter
Advertisement Back2Grow Advertisement

Canada’s cannabis retailers reached a new monthly sales high in August, according to David Brown’s October 23 reporting for StratCann. The reported C$520.4 million total offers an encouraging snapshot of legal retail spending. It also arrives with a reminder for anyone following cannabis numbers: the month being measured, the date of release and the kind of measurement all matter.

This is an August sales story released in October, rather than a measure of what shoppers are spending this week. It is also a national total, which can conceal very different experiences for individual stores, producers and provinces. A record at the cash register does not automatically translate into stronger margins throughout the supply chain.

A record with a revised comparison

StratCann reports that the preliminary August figure was about 3% above the comparable August 2025 total. Its coverage also notes an upward revision to July 2026, from C$503.2 million to C$515.8 million. That revised baseline makes the monthly increase look considerably smaller than a comparison using the older July number would suggest.

The provincial picture was uneven. Brown reports that Alberta declined year over year, while Manitoba recorded the strongest annual percentage increase. Ontario, the largest provincial market by sales, grew by less than 1%. Those differences make a national record a starting point for understanding the market, rather than a description of every local business.

The underlying official series is Statistics Canada’s monthly retail trade table, released October 23. The figures cited here are attributed to StratCann’s reading of that release; the interactive table’s cannabis values were not independently retrievable during our review.

Why revisions belong in the story

Statistics Canada’s Monthly Retail Trade Survey methodology explains that the agency collects information from retailers and administrative records. When actual data are not available during collection, respondents’ estimates can be accepted and revised later. This gives readers a practical reason to check the latest version of a series before making comparisons.

The survey measures monthly retail activity across a changing business population. Its documentation describes sampling, checks for inconsistent responses and estimation for missing information. A release is therefore a statistical estimate with a reference period, rather than an immutable tally that never changes after publication.

For cannabis operators, the useful habit is straightforward: save the release date alongside the number. When comparing two months, use values drawn from the same current version of the series where possible. Otherwise, an apparent jump can partly reflect a stale baseline rather than a sudden change in demand.

Sales dollars and product units answer different questions

A second official source, Health Canada’s cannabis market data, describes what the legal industry sells in packaged units. Its latest displayed product figures cover June 2026, not August. They should not be treated as the product breakdown of the newer retail-dollar record.

For June, dried cannabis accounted for 50% of combined medical and non-medical unit sales, with edibles at 26% and extracts at 23%. These are shares of units, not shares of retail revenue, grams consumed or individual customers. A package of flower and an edible package count as units without necessarily carrying the same price or quantity.

Health Canada also cautions that its information is revised as validation continues, and that it generally does not estimate reports that have not been submitted, except in rare cases. That limitation matters when placing its inventory and sales figures alongside a separate retail survey. The two sources illuminate different parts of the market.

What the record means for readers

For shoppers, the record is evidence of substantial spending in the legal retail channel. It does not establish that cannabis has become cheaper, that every province offers the same selection or that every producer is benefiting equally. Those questions require price, assortment and company-level evidence beyond a national sales total.

The distinction also applies when reading individual business updates, such as Bountiful Farms’ recent retail growth report. A company’s quarterly comparison and a country’s monthly retail series describe different periods and populations. They can provide context for one another without being interchangeable benchmarks.

August’s reported record is worth following. The more useful next step is to watch whether gains persist after revisions and across regions, while keeping dollar sales separate from product-unit measures. That approach gives the headline some substance without asking a single monthly number to explain the entire Canadian cannabis economy.

Keeping a simple reading checklist helps: identify the currency, reference month, release date and whether the measure counts dollars or units. Then check whether the comparison month was revised. Those basic details make a sales headline more useful to someone assessing the market, without assuming a record means every part of the industry is thriving.

Illustrative stock retail photograph; not an identified Canadian retailer. Photo: Lucas Porras / Pexels.

Cannabis

Khalifa Kush Plans a Halloween Debut in New York

Khalifa Kush plans to bring KK and Violet Sky flower and pre-rolls to New York on October 31 through a partnership with cultivator and distributor Skyworld.

Published

on

Dried cannabis flowers beside a glass jar

Khalifa Kush is planning a Halloween entrance into New York’s licensed cannabis market. Wiz Khalifa’s brand says sales are set to begin October 31 through a partnership with New York cultivator and distributor Skyworld. As of October 23, that date is still ahead: this is a preview of an announced launch, rather than a report that the products have already reached stores.

The company’s corrected October 14 announcement identifies two starting cultivars, KK and Violet Sky, in flower and pre-roll formats. It describes an initial rollout to 36 dispensaries: seven in New York City and another 29 across Upstate New York and Long Island. These are the brand’s announced distribution plans, not independently confirmed inventory at every location.

A local partner behind a familiar name

Skyworld will handle New York cultivation and distribution, according to the announcement. That makes the local operation central to what consumers eventually buy. A recognizable national brand name tells only part of the story; the cultivation partner, specific batch and store availability are the details shoppers can check when launch day arrives.

Skyworld’s own website describes the business as Indigenous-owned and New York-based, and lists cultivation, processing and distribution license numbers. It identifies SJR Horticulture, LLC as its operator. The company also provides a lab-results section, giving readers a place to look for product documentation rather than relying solely on launch publicity.

Those details establish how Skyworld presents its operation; they do not substitute for checking the state’s licensing resources or a particular product’s certificate. The announcement also corrected its partner’s name from “Skyworld Cannabis” to “Skyworld.” We use the corrected name here.

KK brings a longer backstory

On its KK product page, Khalifa Kush says the original cultivar was developed for Wiz Khalifa’s personal preferences in the early 2010s. The brand describes a period of private use before its first flower sales at Tryke’s Reef dispensaries in the southwestern United States in 2016. That is the company’s account of the cultivar’s commercial history.

It explains why this New York release carries a recognizable identity before any local customer opens a package. The name connects the artist’s cannabis persona with a product line that has moved through multiple state markets. It is also a reminder that a New York debut is a new distribution milestone for an established brand, rather than the creation of an entirely new cultivar.

The broader KK catalog includes formats beyond flower and pre-rolls. That does not mean all of them are included in the New York opening. The dated announcement is the appropriate guide to the initial local offering; later additions should be reported when the company or retailers confirm them.

Violet Sky adds a different genetic branch

The brand’s Violet Sky page describes a selection effort beginning in early 2021 and a cultivar emerging in late 2022. It identifies the cross as Khalifa Mints and GastroPop, and presents Violet Sky as the third addition to its lineup. Those are breeder and brand descriptions, not independent genetic testing by Cannabis Aficionado.

That distinction is especially useful with cultivar coverage. A lineage can help enthusiasts understand how a company positions a release, but it does not tell an individual reader exactly how a product will feel. We have not sampled these New York batches, and the announcement does not establish their final laboratory results, retail pricing or freshness at any particular shop.

Readers following New York’s plant pipeline can also see our coverage of the state’s upcoming nursery application window. Nursery licensing and a branded retail rollout are separate developments, but both make the people and businesses behind the genetics worth paying attention to.

What to check before making the trip

New York’s Office of Cannabis Management consumer guidance recommends checking the dispensary verification tool displayed at licensed storefronts. It also directs consumers to look for the state’s universal symbol on regulated products and a QR code or link to the batch’s certificate of analysis. The agency’s resources are intended for adults 21 and older.

For a planned launch, store-level confirmation is another practical step. Check a participating dispensary’s current menu or contact the store before traveling. An announced statewide rollout does not establish that both cultivars, every package size or every format will be available at the same time in every shop.

For now, the appeal is a clear date and a focused starting lineup: two cultivars, two formats and a named New York partner. The next reporting milestone is October 31 itself, when actual menus and batch information can show how the promised launch translates into a local shopping experience.

Illustrative stock cannabis photograph; not identified as KK, Violet Sky or Skyworld products. Photo: RDNE Stock project / Pexels.

Continue Reading

Cannabis

Grown Rogue Takes 70% Control of Its New Jersey Cultivation Business

Grown Rogue’s latest ABCO option exercise brings majority board control. The next milestone is turning its planned New Jersey canopy expansion into production.

Published

on

Cannabis plants growing indoors with a blurred cultivation area behind them

Grown Rogue has increased its ownership of ABCO Garden State, its New Jersey cultivation subsidiary, to 70%. The company’s October 20 announcement marks the completion of an ownership step planned well before this autumn. For New Jersey flower buyers, the operational question now is how the company’s next cultivation phase will translate into products reaching dispensary shelves.

The transaction adds 26 percentage points to Grown Rogue’s previous interest and gives it majority control of ABCO’s board. The company says New Jersey regulators approved the second option on September 16. It also says the approximately US$743,000 purchase price had already been advanced in 2023, distinguishing this exercise from a newly announced cash investment of that size.

Ownership and production are separate milestones

In the same announcement, management said it expected Phase II construction to be substantially complete by the end of 2026. The planned result is approximately 16,000 square feet of flowering canopy in New Jersey, with the added capacity ramping into 2027. Those remain company projections, rather than completed construction or flower already available for sale.

A larger ownership interest does not itself create another harvest. Construction, commissioning, cultivation and retail distribution still have to happen. Grown Rogue identifies risks including delays, yield variation, financing constraints and changes in market pricing. Those are meaningful qualifications when assessing how quickly a planned canopy increase could affect consumer choice.

The two-stage deal dates to 2024

The structure is clearer in Grown Rogue’s June 2024 licensing announcement. It reported closing the first option on May 31, 2024, acquiring a 44% interest in ABCO. A second option covered another 26%. At that stage, ABCO held an annual cultivation license and had local zoning and planning approvals.

That earlier release described the first option’s purchase price as roughly US$1.26 million, paid in cash, and anticipated a later regulatory approval for the second stage. Read together, the announcements show a staged entry into an existing state market. They do not describe the purchase of a newly opening retail chain or the legalization of another sales channel.

The distinction matters for readers following expansion headlines. Acquiring equity, obtaining a cultivation license and beginning product sales can take place at different times. A company can be selling in a state before it completes a later ownership option. Here, the 70% milestone follows an operating history already documented by Grown Rogue.

What earlier operating reports show

In an April 2025 cultivation update, the company described preliminary ABCO first-quarter revenue of US$1.8 million and its intention to move from 44% to 70% ownership in autumn 2026. It also explained that much of its investment had been structured as secured lending rather than equity alone.

That update said company loans were to be repaid before distributions to ABCO’s partners. It outlined consulting fees and equity-method reporting as additional parts of the relationship. These historical details help explain why the ownership percentage is only one piece of the business arrangement, rather than a complete account of capital invested or revenue earned.

Grown Rogue subsequently marked the first anniversary of ABCO sales in December 2025, dating the first sale to December 11, 2024. It reported that monthly product sales had exceeded 600 pounds on average over the preceding three months, with more than 80% represented by branded, packaged products. Those are historical company-reported figures, not a current monthly production estimate.

The anniversary update also described growing adoption of Yeti, its value brand, and Phase II construction underway. That product mix gives the expansion a consumer dimension: the business is pursuing both branded flower and a value offering. It does not establish future prices, availability at a particular store or how either line will perform after the next phase ramps.

What to watch next in New Jersey

The next useful update would separate construction completion from the first harvests using the added space, then identify when those products enter distribution. Canopy is a capacity measure; it is not a guarantee of sell-through. Retailer reorders, product consistency and the pace of inventory movement will provide a fuller picture than square footage alone.

For broader state context, our coverage of New Jersey’s cannabis retail proposals follows a different issue: how stores may operate. Grown Rogue’s transaction concerns cultivation ownership. Keeping those subjects separate makes it easier to understand which developments can change supply and which depend on policy decisions.

The completed option gives Grown Rogue more control over a business it has already supported for years. Its coming test is operational execution. Until the expansion produces verified results, readers should treat the projected timetable as management’s plan and the 70% interest as the completed fact.

Illustrative stock cultivation photograph; not an ABCO or Grown Rogue facility. Photo: Kindel Media / Pexels.

Continue Reading

Cannabis

North Carolina’s Cannabis Debate Turns to Who Would Run the Stores

A discussion draft separates private cannabis production from state-controlled retail. The council’s work remains advisory, with major design choices unresolved.

Published

on

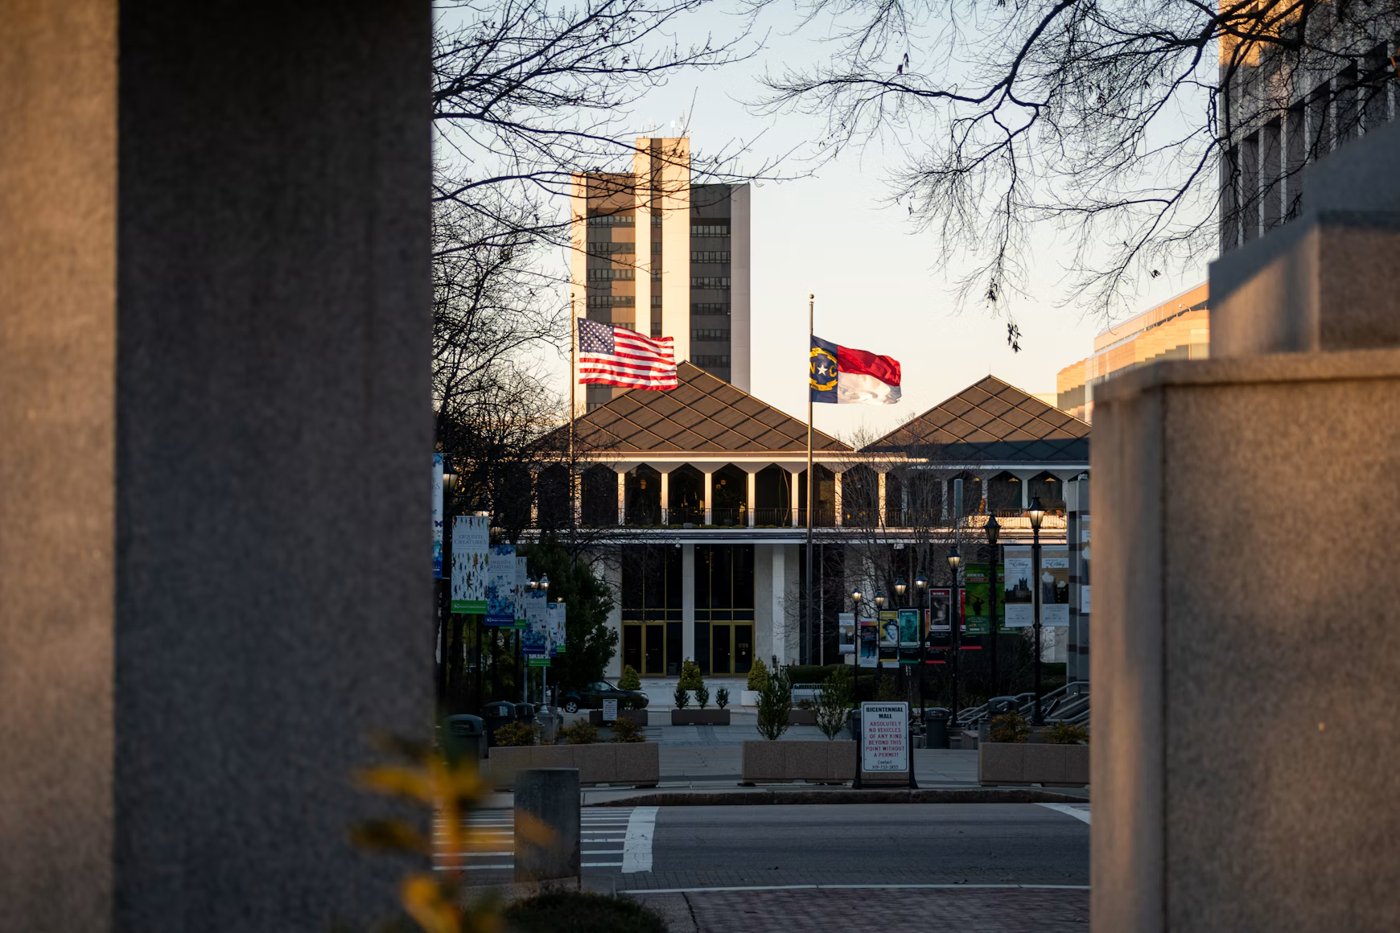
North Carolina Legislative Building in Raleigh with American and state flags

North Carolina’s cannabis policy discussion is moving beyond a yes-or-no argument about legalization to a more practical question: if the state creates a regulated market, who would run it? A licensing discussion draft posted by the governor’s advisory council explores private production paired with state-controlled retail, with a separate pathway for smaller farms.

The distinction is consequential for shoppers and businesses alike. A system can permit adult access while making very different choices about storefront ownership, product distribution and the opportunities available to growers. The document describes options for discussion; it does not create licenses or authorize new stores.

A proposal on the council’s public record

The North Carolina Advisory Council on Cannabis website lists a Market and Regulatory Subcommittee meeting for October 23, alongside further council and subcommittee meetings later in the month. Its materials include a licensing draft associated with the September 18 meeting.

A calendar entry is not a record of a vote. At the time of this review, the posted material establishes the proposal available for discussion, not an adopted October 23 outcome. Readers following the debate should look for subsequent minutes, revised drafts or a final recommendation before treating any option as settled.

Recent reporting by Tony Lange at Cannabis Business Times placed the council’s market-design work within the broader reform debate. The underlying documents are particularly useful because they show how much remains to be decided beneath a general promise of regulation.

Separate the grower, distributor and retailer

The two-page licensing discussion draft outlines three functions: producing, distributing and retailing. Private licensed businesses would cultivate and manufacture, while the retail channel would remain under state control. It draws on North Carolina’s alcohol-control structure and Québec’s cannabis retail approach.

The draft also considers different distribution arrangements, including independent private wholesalers, a state warehouse or a combination. Retail organization has alternatives too: a centralized state system or a decentralized structure involving local boards.

For readers, the important distinction is between controlling the sales channel and operating every part of the supply chain. A government-controlled storefront model need not mean government-grown flower. Likewise, separating production and retail does not settle how products would be selected, priced or made available in different communities.

Those choices deserve separate scrutiny. A retailer’s ownership tells a shopper one thing; the range of producers represented on its shelves tells another. The eventual rules would need to explain how those interests meet.

A craft-farm pathway is part of the discussion

The proposal includes a small-scale craft-farm license alongside standard cultivation and manufacturing categories. It also raises questions about preventing vertical integration and about what forms of common ownership should be prohibited. These remain design questions, not application instructions.

For a smaller grower, a named license category is only a starting point. Practical access would also depend on costs, production allowances and the ability to reach buyers. A future framework could look welcoming on paper while leaving important details unresolved; evaluating it requires reading those details together.

Our reporting on New York’s cannabis nursery application window covers a different part of the same wider issue: rules for supplying the plant can shape a market well before a retail transaction occurs. The two states’ proposals and permissions should not be treated as interchangeable.

Why the council is examining the existing market

The council’s April 2 interim report frames the problem as how to bring an already-existing intoxicating cannabis marketplace under meaningful oversight. It identifies inconsistencies in testing, labeling, packaging and age verification as central concerns.

The report also distinguishes regulation based on the plant’s legal classification from an approach focused on intoxicating cannabinoids. That is a policy argument about consistent oversight, rather than a claim that every product has identical effects or risks.

The report explicitly describes the council as advisory and places authority for changing the state’s framework with the General Assembly. A recommendation, even a detailed one, is therefore a different event from legislation becoming law.

The next documents matter more than predictions

Executive Order No. 16, which established the council in June 2025, calls for final recommendations by December 31, 2026. Its duties extend beyond retail structure to youth protection, public health, impaired driving, justice and administration.

That wider remit is a useful test for the final package. Watch how a proposed sales model connects with product standards, enforcement resources and opportunities for smaller businesses. A credible framework needs those pieces to work together.

North Carolina has a public set of questions about what regulated cannabis could look like. The news to watch next is which answers the council recommends and which, if any, lawmakers turn into enforceable rules.

North Carolina Legislative Building in Raleigh. Archival stock photograph; not a photograph of the advisory council meeting. Photo: Elijah Mears / Unsplash.

Continue Reading

Trending

Join The Cannabis Aficionado Community!
Join the Cannabis Aficionado community and receive all of the most relevant news geared towards our sophisticated enthusiast community.
Loading

Copyright ©️ 2026 Cannabis Aficionado. Cannabis Aficionado is a registered trademark of CNM Inc. All rights reserved. Registration on or use of this site constitutes acceptance of our Terms of Service, Privacy Policy and Cookies Policy. People may receive compensation for some links to products and services. Offers may be subject to change without notice.