A new appeal from 16 governors is putting cannabis banking back before Congress, with the focus on ordinary business functions: deposits, payroll, lending and the safety of handling cash. The request concerns the financial infrastructure behind state-sanctioned cannabis businesses, rather than a new authorization to sell marijuana nationwide.
Tom Angell reported for Marijuana Moment on November 10 that the governors sent congressional leaders a letter supporting the SAFE Banking Act. Maryland Governor Wes Moore led the appeal. The report identifies all 16 signatories as Democrats; the legislation they support has bipartisan sponsors.
The request reaches beyond the dispensary counter
The governors’ argument is that reliance on cash creates problems for workers, businesses and state oversight. A customer may notice only the payment method at checkout, but a retailer also needs to pay employees, manage accounts and move money without treating each routine transaction as an exceptional problem.
A legislative appeal does not mean Congress has passed the measure. It also does not establish that every cannabis business lacks a bank account. The more useful question is which services a business can obtain, on what terms, and whether that access remains reliable.
The Government Accountability Office’s banking review, publicly released September 8, provides evidence of that more complicated picture. It found that some financial institutions serve cannabis-related businesses while others are deterred by legal concerns and the expense of meeting compliance requirements.
A bank account is only one part of access
GAO heard from owners and managers who described account closures, expensive accounts and costly business loans. Those are different obstacles. Opening an account does not necessarily solve borrowing needs, and having a lender does not guarantee that every customer payment method will be available.
The report also describes difficulties for people employed in the industry when seeking personal financial services. That broadens the story beyond a company’s balance sheet. Someone working for a licensed cannabis business can encounter consequences connected to their employer’s sector, even when applying for an ordinary personal service.
For customers, the payment question remains especially visible. GAO reported that two major credit-card companies prohibit cannabis purchases. The finding helps explain why a legal retail setting can still have a different checkout experience from other shops. A proposed banking change should not be described as an immediate promise that every card will work.
Existing guidance does not eliminate every barrier
GAO points to federal guidance issued by the Financial Crimes Enforcement Network in 2014. It describes how financial institutions can serve cannabis-related businesses while meeting Bank Secrecy Act responsibilities, including gathering detailed customer information and filing specified suspicious-activity reports.
Those requirements help explain why the decision is not simply whether a bank likes cannabis. Institutions weigh ongoing obligations, costs and perceived legal exposure. The report says some choose to serve the sector to meet community needs or because they see a business opportunity.
The distinction between permission, obligation and willingness matters. Guidance can explain a compliance route without requiring a financial institution to offer a particular account, loan or payment service. That is why the existence of guidance and continued access problems are not necessarily contradictory.
Count the data carefully
GAO reviewed FinCEN data showing that roughly 1,000 banks and credit unions filed cannabis-related suspicious-activity reports in 2024. The agency cautioned that this is not an exact count of institutions maintaining ongoing cannabis-business customers. A report could involve an occasional transaction or an ancillary business rather than a plant-touching operator.
That caveat is important when banking statistics appear in reform debates. A large number of reports does not reveal how easily an individual dispensary can obtain a loan, what its fees are, or whether a service will remain available next month.
The review combined agency documents and reporting data with focus groups and interviews. Its financial-institution work involved 74 institutions; separate focus groups included owners and managers from 51 cannabis-related businesses. Those methods provide useful accounts of barriers, but they should not be mistaken for a survey of every bank and dispensary.
What the new appeal changes
The governors’ letter adds current political pressure to an existing operational problem. Its immediate result is a renewed request for congressional action, not a completed banking overhaul. The next development to watch is legislative movement and the exact protections any final text contains.
Our report on Weedmaps parent WM Technology’s quarterly results examined a different business pressure: paying clients and advertising budgets. Together, the stories show why the cannabis economy involves more than consumer demand. Businesses also need workable payment systems, dependable accounts and the ability to manage everyday obligations.
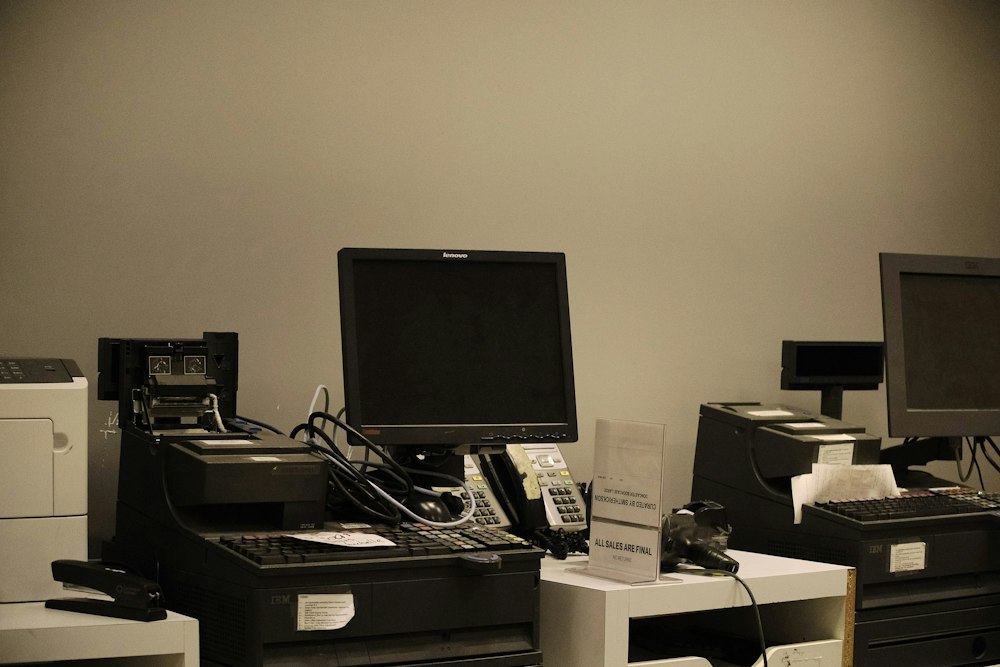
Illustrative retail checkout photograph; not a cannabis business or a U.S. bank. Photo: Allen Y / Unsplash.

 Cannabis3 weeks ago
 Cannabis3 weeks ago
 Cannabis3 weeks ago
 Cannabis3 weeks ago
 Cannabis3 weeks ago
 Cannabis3 weeks ago
 Cannabis3 weeks ago