#cannabisaficionado

Industry Innovators

Aurora Sets December 23 Shareholder Meeting as Organigram Deal Advances

A December 23 virtual meeting and November 18 record date put the next stages of Aurora’s proposed Organigram acquisition on the calendar.

Published

on

A laptop on a white conference table surrounded by office chairs
Advertisement Back2Grow Advertisement

Aurora Cannabis has put a December 23 virtual special shareholder meeting on the calendar, bringing a practical deadline into focus for investors following its proposed acquisition by Organigram. A notice from transfer agent Computershare also sets November 18 as the record date for meeting notices and voting. The cannabis companies remain separate businesses while the transaction works through its approval process.

The meeting notice is dated November 9. It is a calendar update worth watching ahead of Wednesday’s record date, rather than a new acquisition announcement on November 16. Organigram and Aurora announced their agreement November 3, following its signing the previous day.

Two dates with different jobs

The record date and meeting date serve different purposes. November 18 establishes the ownership reference date identified in the notice; December 23 is the listed date for the special meeting. Neither date is the transaction’s closing date. The notice identifies the meeting as virtual, so shareholders should look for participation instructions in the formal meeting materials.

That distinction matters for people holding shares through a broker. A date on a corporate calendar does not supply the individual voting instructions, control number or submission deadline applicable to an account. Those details need to come from the shareholder materials and the relevant intermediary. This brief notice does not provide them.

What shareholders are being asked to consider

The companies’ November 3 joint announcement described an acquisition of all Aurora common shares, valuing Aurora at approximately C$561 million on a fully diluted equity basis. It offered cash, Organigram shares or a combination, with the cash-only and share-only elections subject to proration.

In practical terms, the election choices must be read alongside the allocation rules. Choosing cash or stock does not mean every shareholder can receive an unlimited amount of their preferred form of payment. Our earlier coverage of the acquisition agreement explains the proposal’s background and the competing approach that preceded it.

The companies framed the combination around Organigram’s Canadian recreational business and Aurora’s international medical cannabis platform. Their stated ambition is a larger network spanning production and market access. Those are management’s strategic expectations, with the eventual operating results still to be demonstrated.

A meeting is one part of the approval chain

Organigram’s material change report describes a threshold of at least two-thirds of votes cast by Aurora shareholders present or represented by proxy. A separate minority-vote requirement may apply. Organigram also needs shareholder approval for its share issuance, including a vote excluding British American Tobacco’s holding and other required exclusions.

The same report lists court, exchange and regulatory conditions. These include approval from the Supreme Court of British Columbia, Canadian competition approval and German foreign-investment clearance. A favorable shareholder vote would therefore advance the transaction without, by itself, completing the acquisition.

The report describes an expected January 2027 closing and says closing cannot occur before January 6. That timetable is a forecast subject to the outstanding conditions. December 23 should consequently be treated as a governance milestone, not the date patients or customers automatically begin dealing with a combined company.

There is also a distinction between the two companies’ meetings. The Computershare document establishes Aurora’s date; the material change report describes the intended meeting timetable for both companies. Shareholders should not use one issuer’s notice as a substitute for the other’s formal instructions. Each voting process has its own resolution and electorate, even though both relate to the same proposed combination.

What the calendar means beyond the stock market

For medical cannabis patients, a corporate transaction raises concrete questions about ordering, product continuity and service. For recreational customers, the questions may concern brands and availability. The meeting notice makes no product-level commitments and gives no basis for assuming a particular item will disappear or a distribution channel will change.

Those questions are better answered by subsequent company communications about specific operations. The useful development here is a clearer sequence: establish the meeting’s ownership reference date, distribute the detailed materials, hold the vote and satisfy the remaining conditions. Each stage produces evidence that can be assessed separately.

Shareholders following the proposal should distinguish the board’s recommendation from their own voting decision, and the proposed transaction terms from the current market value of either company’s shares. The full materials will be more informative than a headline valuation alone, especially where consideration includes shares and allocation rules.

The next documents to watch are the formal circular and voting instructions, followed by the meeting outcome and regulatory updates. A dated meeting gives the process a firmer shape. Evidence of completed approvals will determine when the proposed cannabis combination becomes an operating reality.

Illustrative stock office photograph; not an Aurora or Organigram facility or meeting. Aurora’s listed meeting is virtual. Photo: cottonbro studio / Pexels.

Industry Innovators

Trulieve’s Preliminary Russell Inclusion Puts a December Market Milestone Ahead

Trulieve’s preliminary Russell 2000 and 3000 inclusion is a stock-market milestone, with final changes scheduled for December 11.

Published

on

Hands using a calculator beside a stack of documents on a desk

Trulieve Cannabis says it is set to enter the Russell 2000 and Russell 3000 indexes, a development that could bring its shares into a more widely followed set of U.S. market benchmarks. The company announced the preliminary inclusion November 16. Final membership changes are scheduled to take effect after U.S. markets close December 11.

The distinction between a preliminary list and implemented membership is central to the story. FTSE Russell’s November 13 additions document names Trulieve Cannabis Corp., ticker TRLV. It provides direct evidence of the proposed Russell 3000 addition, beyond the cannabis operator’s own announcement.

What the two index names mean

The Russell 2000 represents the smaller-company segment within the broader Russell 3000. Naming both benchmarks does not describe two separate capital raises or two new stock-exchange listings. It identifies overlapping parts of an index family used to organize and compare the U.S. equity market.

In its announcement, Trulieve linked the development to its New York Stock Exchange listing and U.S. domestication. Chief executive Kim Rivers said index inclusion could increase awareness, liquidity and access to institutional investors. Those are the company’s expectations, rather than a measured outcome established by appearing on the list.

An index is a benchmark; a fund is an investment vehicle with its own mandate. Some funds seek to track an index, while active managers may use one to judge performance. That difference matters when assessing claims about how many investors will buy a newly included company and how much money might follow.

The December process is still running

FTSE Russell’s reconstitution calendar sets October 30 as the ranking date for this review. The preliminary lists began November 13, with further updates listed for November 20, November 27 and December 4. Implementation follows the December 11 market close.

That sequence gives investors several checkpoints between Monday’s announcement and the revised indexes taking effect. Readers assessing Trulieve’s status should consult the current list as the process advances, rather than treating the first announcement as confirmation that every implementation step has already occurred.

The provider returned to a twice-yearly reconstitution schedule in 2026. Its November 13 overview describes June and December reviews designed to reflect changes in the U.S. market. For this December round, it expects 125 companies to join the Russell 2000, placing Trulieve’s announcement within a much broader market exercise.

Size and eligibility differ from business quality

The provider’s ground rules explain that membership eligibility uses public information available on the ranking date and market capitalization calculated at that day’s close. The methodology also addresses the shares available to the public, commonly described as free float.

These are rules for constructing a market benchmark. Inclusion does not amount to an analyst’s recommendation or a finding that a company’s earnings, products or future returns are superior. For cannabis businesses in particular, market recognition and operating performance should be examined as separate questions.

The distinction also helps explain the scale figures surrounding reconstitution. FTSE Russell estimates approximately $12.5 trillion is benchmarked to, or invested in products based on, its U.S. indexes. That family-wide figure is not a pool earmarked for Trulieve, and it includes benchmarked assets rather than only passive funds compelled to mirror holdings.

For example, buying existing shares in the market transfers ownership between investors. A company issuing new shares to raise capital is a different transaction. The index announcement identifies no new offering proceeds for Trulieve, so interpreting inclusion as a direct addition to its cash balance would misread the event.

Likewise, a benchmark’s sector classification organizes securities for investment analysis. The additions document places Trulieve in Health Care, but that classification does not constitute approval of a specific cannabis treatment or product. The label serves an index-construction purpose and should be understood within that context.

What cannabis readers can watch next

For people following the industry, the immediate relevance is how an established cannabis operator fits into mainstream equity-market infrastructure. The preliminary addition concerns ownership and trading of its shares. It does not announce a new dispensary, a change in patient eligibility or a product launch.

It should also be kept separate from the sector’s banking-policy debate. Our coverage of governors’ renewed cannabis banking push follows a different question: access to everyday financial services. A benchmark decision does not resolve the policy issues discussed there.

The next useful evidence will be the updated membership lists and December implementation, followed by actual trading and operating disclosures. Trulieve has a documented place on the preliminary additions list. Whether that translates into sustained liquidity or a different investor base will require evidence after the milestone, rather than an assumption about a guaranteed share-price response.

Illustrative stock photograph of document review; not Trulieve personnel, records or premises. Photo: Mikhail Nilov / Pexels.

Continue Reading

Industry Innovators

Glass House’s Record Harvest Meets Lower Cannabis Prices in Q3

Glass House reported record cannabis production and higher revenue, while lower selling prices and a trim-heavy mix kept pressure on margins.

Published

on

Rows of potted nursery plants beneath a greenhouse roof

Glass House Brands reported record cannabis production and higher third-quarter revenue on November 16, but its larger harvest met a lower selling price. Revenue reached $56.8 million, compared with $47.0 million in the preceding quarter. Gross margin fell to 26 percent from 34 percent, showing why more production and lower cultivation costs do not automatically produce stronger earnings.

The results cover the three months ended September 30 and are expressed in U.S. dollars. They add a fuller earnings account to preliminary figures released in October. The latest release reports a $10.1 million net loss and positive adjusted EBITDA of $0.8 million. Those measures describe different aspects of the business; positive adjusted EBITDA is not the same as a profit.

More pounds, less revenue per pound

The company’s November 16 results release puts production at 319,052 equivalent dry pounds, up from 245,746 in the second quarter. Its reported production cost declined to $109 per pound from $122. The average selling price, however, fell to $151 per pound from $211 over the same comparison.

That combination is the operating story behind the headline growth. The company was producing more efficiently by its own cost measure while receiving less per pound sold. A lower cultivation cost can help, but it does not neutralize every change in pricing, product mix or the expense of running the wider business.

The price and cost figures also should not be read as a complete per-pound net profit calculation. Corporate expenses and other accounting items sit outside a simple subtraction of the two. Readers need the financial statements and the definitions of the operating measures to understand what each number includes.

The mix of what gets sold matters

In its management discussion and analysis, Glass House reports quarterly net revenue of about $56.8 million and gross profit of approximately $14.6 million. The broader report separates the wholesale biomass business from packaged consumer products and explains the effect of the retail operation’s deconsolidation on presentation.

The results release attributes margin pressure to seasonally lower prices and a greater proportion of trim. A pound is therefore not a uniform commercial outcome. What is harvested, its quality category and the form in which it is sold can matter alongside the volume. Record production alone cannot establish the value of that production to the company.

The reporting structure is another reason to read comparisons carefully. Glass House Retail was deconsolidated in June, and historical operating results have been recast. A reader comparing an old headline with the current release should first confirm that both figures refer to the same scope of operations. A change in accounting presentation is different from a change in customer demand.

October’s preliminary figures were a checkpoint

The company’s October 19 preliminary announcement already indicated revenue of $56.8 million, approximately 317,000 pounds of production and a production cost near $110 per pound. It also put estimated gross profit at $14.9 million. Monday’s release provides updated figures rather than an entirely unexpected first account of the quarter.

The distinction matters for readers following company announcements over time. Preliminary operational estimates can be useful, but they should remain identified as preliminary. The later report refines some numbers and adds more complete earnings information. Carrying every October figure forward without checking it would miss that progression.

October’s announcement also described funds raised through the company’s at-the-market share program and warrants, with intended uses including greenhouse expansion, automation and facility upgrades. Money raised for a project is a financing fact; the future operating benefit of spending it is a separate question. Neither should be substituted for cash generated through ordinary operations.

Earnings and cash still need their own review

The latest release reports slightly negative quarterly operating cash flow, approximately $0.1 million. It also reports cash and restricted cash of $39.7 million at quarter-end. A cash balance, a financing inflow and operating cash flow are distinct measures, and combining them can obscure whether the core business is funding itself.

Our Rubicon results coverage makes a related distinction between sales growth and the economics of scaling cultivation. The companies operate in different markets and report in different currencies, so the comparison is conceptual rather than a direct ranking of their figures.

For Glass House, the next useful evidence will connect production, saleable mix, realized prices and cash generation. The company’s production forecasts and long-term cost targets remain management expectations. This quarter establishes a larger harvest and higher sales, alongside thinner sequential margins and a net loss. The operating improvement has to be assessed with all of those facts in view.

Illustrative plant-nursery photograph; not a cannabis crop or a Glass House facility. Photo: Anna Shvets / Pexels.

Continue Reading

Industry Innovators

Rubicon’s Revenue Grows as Cascadia’s Slow Ramp Pressures Earnings

Rubicon reported higher third-quarter cannabis revenue, but a delayed Cascadia ramp weighed on margins and adjusted earnings.

Published

on

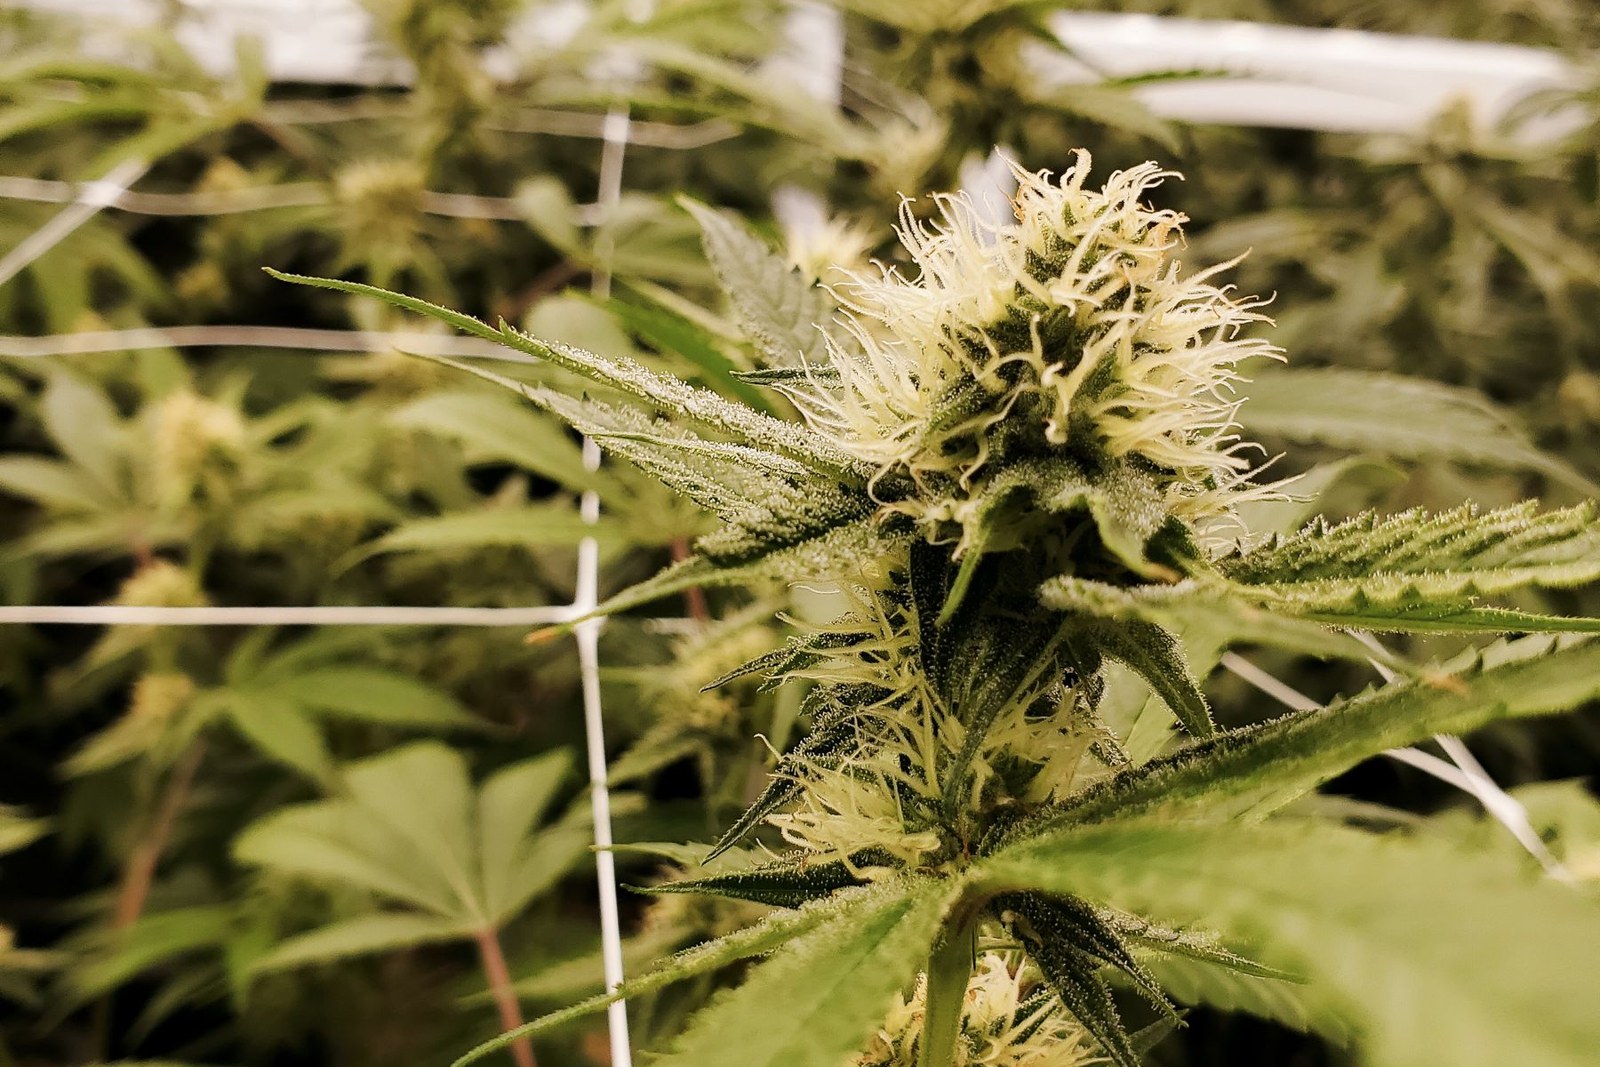
A flowering cannabis plant growing through a support net

Rubicon Organics reported higher cannabis sales for its third quarter on November 16, but the growth came with a harder operating picture. Net revenue rose 17 percent from a year earlier to C$18.3 million, while adjusted EBITDA fell 17 percent to about C$1.4 million. Management said its Cascadia cultivation facility was roughly six months behind its initial production ramp.

The results, covering the three months ended September 30, offer a useful test of a familiar cannabis-business promise: more cultivation capacity can support growth, but the expense arrives before a facility necessarily reaches its intended output. Rubicon’s latest numbers show why sales, production targets and profitability need to be read together. All financial amounts here are Canadian dollars.

Higher sales did not produce higher margins

The unaudited financial statements put quarterly net revenue at C$18.260 million, compared with C$15.628 million a year earlier. Cost of sales rose to C$13.242 million from C$10.367 million. Gross profit before fair-value adjustments consequently declined to C$5.018 million from C$5.261 million, despite the stronger revenue.

That is the central tension in the report. Selling more product did not prevent the underlying gross-profit dollars from falling. For a cultivator scaling a facility, higher throughput is commercially useful only if the added revenue can absorb the operating cost attached to it.

The statements show a quarterly net loss of C$105,000, compared with net income of C$2.826 million in the comparable period. These are unaudited interim accounts; the accompanying notice says the independent auditor has not reviewed them. That qualification belongs alongside the figures when assessing the report.

What adjusted EBITDA leaves out

Rubicon’s management discussion and analysis records adjusted EBITDA of C$1.435 million, against C$1.739 million a year earlier. The reconciliation matters because this is a company-defined non-GAAP measure, rather than net profit or cash generated by operations. Its adjustments include depreciation, share-based compensation and cannabis fair-value accounting.

The treatment of Cascadia also changed. Pre-revenue startup costs were excluded from the adjusted measure in earlier periods; beginning in this quarter, those costs were no longer excluded. That makes the facility’s transition into revenue production important to understanding the comparison, rather than simply reading the percentage change as a stand-alone verdict.

There was sequential improvement: adjusted EBITDA was above the second quarter’s C$1.128 million. Net revenue, however, was slightly below the second quarter’s C$18.452 million. The latest quarter therefore supports a mixed description: annual sales growth, a modest sequential sales decline and stronger adjusted earnings than the preceding quarter.

Cascadia is now an execution question

In its results announcement, Rubicon said Cascadia contributed approximately C$2.3 million of quarterly revenue. Management described the site as about six months behind the original ramp and said it was working toward target yields by year-end. That is a management objective, not a result already achieved.

The company also pointed to production improvements at Pacifica, international sales and manufacturing investment. International markets represented 11.7 percent of quarterly net revenue, according to the release. Those channels offer another source of sales, while adding a separate question about whether export growth can be sustained alongside domestic demand.

For readers following the business, the relevant next disclosure is more than a larger harvest. It is whether consistent output converts into saleable inventory, recognized revenue and a healthier margin. Capacity announcements cannot establish those steps in advance, and this quarter’s sales increase illustrates why checking the conversion matters.

The August second-quarter announcement had already described profitability pressure from scaling Cascadia, while emphasizing rising sales and Pacifica yield improvements. The latest report therefore follows an existing operational issue. The change to watch is whether that investment phase moves toward consistent margins, rather than whether management continues to describe a growth opportunity.

Expansion targets still need operating evidence

We previously covered Rubicon’s financing for Pacifica lighting upgrades. That story concerned an investment and future capacity; Monday’s earnings report adds a later operating checkpoint. Keeping those events separate avoids presenting a capital raise as proof that its intended production gains have already arrived.

The distinction is particularly important in cannabis, where a cultivation plan can sound concrete because it is expressed in kilograms. A capacity number describes potential production under stated assumptions. It does not tell readers how much flower will meet specifications, when customers will buy it or what the business will retain after costs.

The next results should help test whether the delayed ramp is narrowing and whether spending begins to translate into better economics. Until then, Rubicon has reported real revenue growth alongside real margin pressure. Both belong in the account of the quarter, with future yield and capacity goals clearly identified as forecasts.

Illustrative cannabis cultivation photograph; not a Rubicon facility or named cultivar. Photo: Teanna Morgan / Pexels.

Continue Reading

Trending

Join The Cannabis Aficionado Community!
Join the Cannabis Aficionado community and receive all of the most relevant news geared towards our sophisticated enthusiast community.
Loading

Copyright ©️ 2026 Cannabis Aficionado. Cannabis Aficionado is a registered trademark of CNM Inc. All rights reserved. Registration on or use of this site constitutes acceptance of our Terms of Service, Privacy Policy and Cookies Policy. People may receive compensation for some links to products and services. Offers may be subject to change without notice.