#cannabisaficionado

Industry Innovators

Hydrofarm Trades a $109 Million Loan for a New Ownership Structure

A financing and debt exchange give the cultivation supplier a different balance sheet. The terms explain why debt relief and operating recovery are separate questions.

Published

on

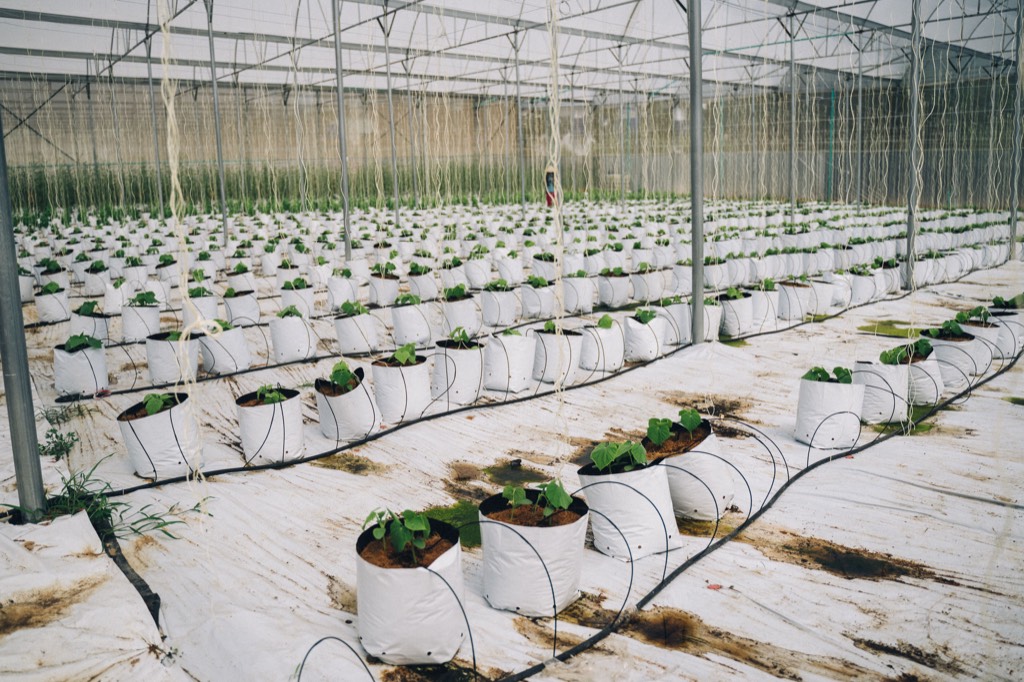
Rows of young plants in white growing bags inside a greenhouse
Advertisement Back2Grow Advertisement

Hydrofarm has closed a financing and lender exchange that remove a major term loan while changing the ownership claims around the cultivation-supply business. The company announced the completed transactions October 28, following an October 27 closing. For growers who know the company through equipment and cultivation inputs, the development is about the financial structure behind that supplier.

The headline numbers need to be read separately, with the cash financing distinguished from the securities issued to lenders. Approximately $8.3 million in gross financing proceeds and the elimination of a term loan with approximately $109 million in principal do not describe a simple cash repayment. The lenders received securities as part of the exchange.

Fresh capital alongside a lender exchange

In its October 28 announcement, Hydrofarm said the financing combined a registered direct offering with a concurrent private placement. The $8.3 million figure is before placement fees and expenses; net proceeds are intended for general corporate purposes. The company says the transactions eliminate approximately $12 million in annual debt service.

Hydrofarm describes its business as manufacturing and distributing controlled-environment agriculture supplies, including plant nutrition, growing media, lighting and climate-control solutions. The announcement is a supplier financing update, rather than a new cannabis product launch or an announcement that growers have increased their purchases.

What lenders received

The company’s October 27 Form 8-K records the loan obligations as discharged at closing. The lender consideration includes 27.5 million non-voting convertible preferred shares and warrants to purchase another 27.5 million common shares at $0.78 each. Preferred conversion and exercise of those lender warrants depend on stockholder approval.

The filing gives the preferred shares priority over common shares in the specified capital structure and describes a one-for-one conversion mechanism, subject to approval and ownership limits. Those details explain why retiring a loan does not remove every claim on the business. The form of the lenders’ position changes.

For an existing common shareholder, the relevant follow-up question is how many shares could ultimately be outstanding. A financing headline alone cannot answer that. It requires reading the separate instruments, their conversion or exercise conditions, and the subsequent stockholder materials together.

Why the type of security matters

The SEC’s Investor.gov guide to stocks distinguishes ownership securities from ordinary borrowing. It explains that companies may issue shares to fund operations or repay debt, and that preferred stock generally has a different place from common stock in the order of distributions and liquidation claims.

Those general descriptions are a starting point, not a replacement for Hydrofarm’s specific terms. A reader should not assume that every preferred share has the same voting, dividend or conversion rights. The actual certificate and transaction documents determine the rights attached to this issue.

The same care applies to warrants. The lender warrants represent a conditional right to acquire common shares under their terms. Their stated share count should not be described as common shares already issued through an exercise that has yet to satisfy its conditions.

Listing compliance remains a company position

The 8-K says Hydrofarm believes its pro forma equity exceeds Nasdaq’s $2.5 million minimum and that it has regained compliance with the relevant equity rule. It also states that the company remains subject to the Nasdaq Hearings Panel’s review and continued monitoring. That is not an independently confirmed clearance from Nasdaq.

A reader can acknowledge the completed financing while leaving that separate determination open. The next useful evidence would be the exchange’s response and the company’s subsequent disclosures. Treating a management belief as a final regulator or exchange decision would skip a material part of the story.

The operating test comes after the transaction

The SEC’s guide to financial statements explains why several statements are needed to understand a business. A balance sheet records assets, liabilities and equity at a point in time. An income statement measures revenue and expenses over a period, while the cash-flow statement shows how cash moved through operating, investing and financing activities.

Applied here, that framework suggests three different questions. What obligations changed at closing? What did the company spend to complete the financing? And, in later reporting periods, can the underlying business generate cash from customers after operating costs? An improvement in one area is meaningful without proving all three have been resolved.

For cultivation businesses evaluating a supplier, the practical focus remains product availability, service and the commercial terms offered to them. This financing does not establish that any of those have changed. Hydrofarm has completed a substantial financial reset; the evidence for an operating recovery will come from what the business reports and delivers afterward.

Illustrative stock greenhouse; not a Hydrofarm facility or identified customer. Photo: Anna Tarazevich / Pexels.

Industry Innovators

Auxly’s Cannabis Sales Rise as Last Year’s One-Time Gain Complicates the Profit Comparison

The Canadian cannabis producer’s revenue and operating cash figures improved, while its headline net-income comparison tells a different story.

Published

on

An aisle between warehouse racks filled with cardboard boxes

Auxly’s third-quarter cannabis results offer two headlines that need to be read together. Net revenue increased 24 percent from a year earlier to C$49.5 million, while reported net income declined. The difference does not mean the sales growth disappeared; it reflects, in part, a comparison with a prior-year quarter containing a substantial one-time gain.

The Canadian cannabis producer released its results November 12, 2026 for the three months ended September 30. Its accompanying financial statements and management discussion are dated November 11. Amounts here are Canadian dollars, avoiding a misleading comparison with U.S.-dollar figures reported by other cannabis companies.

Sales growth and the profit comparison

Auxly’s news release reports adjusted EBITDA of C$15.8 million, up 29 percent, and net income of C$13.6 million, compared with C$20.5 million a year earlier. Management notes that the 2025 comparison included a C$8.1 million after-tax gain related to the Imperial debenture settlement.

That creates a reason to examine the components of earnings rather than selecting whichever headline looks most dramatic. A settlement gain can raise reported profit without representing repeatable sales of cannabis. Conversely, removing selected items produces a different measure whose definition and reconciliation still need to be understood.

Adjusted EBITDA is not the same as net income, and neither is simply the amount of cash available for expansion. Auxly identifies adjusted EBITDA as a non-GAAP measure and directs readers to its reconciliation. The useful comparison is between consistently defined measures over time, with the excluded items visible.

The financial statements add a cash distinction

The interim statements report C$14.3 million of net cash provided by operating activities during the quarter. That differs from the C$14.8 million figure before working-capital changes highlighted in the announcement. Both can be accurate because they describe different stages of the cash-flow calculation.

Working capital includes movements in items such as receivables and inventory. A measure calculated before those movements helps isolate one aspect of performance, but it cannot answer every question about cash actually generated during the period. The statements provide the bridge between the two numbers.

At September 30, the statements show C$51.4 million in cash and cash equivalents. That is a balance at a particular date. It should not be confused with the quarter’s revenue, its net income or a promise that the entire balance will be spent on new production.

The statements also label the interim figures unaudited and explain that share and per-share amounts reflect the July 28 share consolidation. Those details matter when comparing old share counts or earnings per share, even though they do not change the basic story about cannabis sales.

Flower and pre-rolls remain central

The management discussion says dried flower and pre-roll products accounted for approximately 64 percent of quarterly net revenue, with the balance from the company’s other cannabis product categories. It attributes year-over-year sales growth to higher volumes across core products and improved flower pricing, partly offset by pressure on vape prices.

That is more informative for readers following the cannabis shelf than an undifferentiated growth percentage. Different formats can move in different directions at the same company. Higher total revenue does not establish that every product category gained pricing power or that every retailer saw the same demand.

The filing also describes the role of Auxly Leamington in cultivation and processing. An integrated production footprint can support supply, but its existence alone does not demonstrate consumer preference, product quality or a future sales result. Those claims require evidence beyond the size of a facility.

The previous quarter supplies context

Auxly’s August 13 second-quarter announcement reported C$45.8 million in net revenue and C$14.3 million in adjusted EBITDA. The third-quarter figures are higher than those earlier results, as well as higher than the year-earlier revenue and adjusted EBITDA comparisons. That is a useful check on the direction of the reported business.

Quarter-to-quarter changes are still different from a sustained trend. Product launches, customer ordering and seasonal patterns can affect individual periods. A single quarter does not establish the eventual return on a capital project or the success of an export strategy.

Our earlier coverage of Weedmaps’ tougher advertising quarter illustrated another part of the cannabis economy. The companies have different business models and reporting measures, so their results should not be treated as interchangeable signals for the whole industry.

For Auxly, the next useful tests are continued demand, cash generation after working-capital movements and the results of planned investments. The present filing supports a specific conclusion: cannabis revenue and several operating indicators improved, while the reported net-income comparison requires attention to last year’s exceptional items.

Illustrative warehouse stock photograph; not an Auxly facility or identified cannabis inventory. Photo: Russ Murray / Unsplash.

Continue Reading

Cannabis

Charlotte’s Web Reports Lower CBD Sales but a Narrower Quarterly Operating Loss

The hemp-derived CBD company’s latest results show why lower revenue and an improving quarterly loss can coexist—and why neither resolves the policy outlook.

Published

on

Empty amber glass bottles arranged on a light surface

Charlotte’s Web reported a difficult sales quarter for its hemp-derived CBD business while narrowing its operating loss. Revenue for the three months ended September 30, 2026 was US$9.4 million, down 18.3 percent from a year earlier. Its operating loss narrowed to US$3.7 million from US$5.3 million, showing why the direction of sales and the direction of a loss do not always match.

The company announced the results November 12 and filed its quarterly report with the U.S. Securities and Exchange Commission. The release attributes weaker revenue primarily to California restrictions that took effect in July, reduced promotional discounting and softer demand in parts of the hemp-wellness market. Those explanations are management’s account of the quarter, rather than an independent measurement of every factor affecting CBD shoppers.

Less revenue does not automatically mean a larger loss

The company’s earnings release reports quarterly gross profit of about US$4.4 million, compared with US$4.5 million a year earlier, even as sales fell. Gross margin improved to 46.9 percent from 38.9 percent. Selling, general and administrative expenses declined to US$8.1 million from US$9.7 million.

A percentage margin and a dollar profit measure answer different questions. A company can retain a larger share of each sales dollar while bringing in fewer dollars overall. Lower expenses can then narrow the operating loss without putting the business into operating profit. That is the distinction these results require.

The announcement also identifies an inventory reserve linked to simplifying the product range. Readers should therefore resist interpreting a single margin percentage as a permanent new baseline. Product mix, pricing, manufacturing costs and inventory adjustments can all affect the calculation.

The quarterly filing keeps the periods straight

The Form 10-Q records quarterly revenue more precisely at US$9.393 million and a net loss of US$3.458 million. These rounded to the US$9.4 million revenue and US$3.5 million net loss in the announcement. An operating loss and a net loss are different lines of the accounts, not conflicting reports of one number.

The nine-month picture is also distinct from the latest quarter. The release reports a US$20.7 million net loss for the first nine months, including noncash items associated with the earlier debenture conversion. It would be misleading to describe an improved third-quarter operating loss as proof that every year-to-date earnings measure improved.

The filing shows US$11.364 million of cash and cash equivalents at September 30. Cash on that date is a financial-position measure, rather than sales or profit earned during the quarter. Looking at the income statement and cash-flow statement together gives a fuller picture than treating a positive cash balance as evidence of profitability.

Hemp policy remains part of the business story

Cannabis policy is directly relevant to this CBD company because the legal definition of hemp determines which products can use that route to market. The Congressional Research Service’s October 28 legal sidebar explains that the federal delay does not move every element of the new definition to the same date. It distinguishes the treatment of certain cannabinoids not naturally produced by the plant from provisions delayed until December 11.

That distinction is useful beyond one company. A hemp-derived label does not settle a product’s future legal status, and a federal deadline does not automatically override a state’s separate rules. Consumers and businesses need to identify the applicable product definition, ingredients and jurisdiction.

Charlotte’s Web’s October 28 announcement said it planned to hold a corporate update after December 11 rather than a November earnings call, seeking greater policy clarity before discussing its outlook. That is a communications plan, not evidence that Congress will produce the outcome the company prefers.

Product access and medical evidence are separate

A financial report from a CBD business does not establish that a product treats a disease or is appropriate for a particular person. Sales trends describe commercial activity. They do not measure a clinical benefit, and a discussion of future healthcare distribution should not be mistaken for a new drug approval or a general reimbursement entitlement.

Our coverage of Willie Nelson’s hemp-policy appeal addresses the public debate over access. Charlotte’s Web’s results supply a different perspective: how a company says restrictions, pricing decisions and expenses are affecting its accounts. The two stories illuminate different parts of the same policy uncertainty.

The next meaningful business signals will include the durability of any sales recovery, spending levels and the details of the legal framework actually in force. For now, the results show a smaller quarterly operating loss alongside lower CBD revenue. They do not yet resolve whether the company can turn that improvement into sustained growth and profitability.

Illustrative empty-bottle stock photograph; not Charlotte’s Web packaging or identified CBD products. Photo: Kelly Sikkema / Unsplash.

Continue Reading

Industry Innovators

Portland Weighs Cannabis Pickup Windows and Licensing Payment Changes

Portland’s cannabis pickup-window and licensing proposal remains under review, with the city record listing a December 8 committee meeting.

Published

on

Portland waterfront buildings seen across the river

Portland is considering removing a city-code restriction on cannabis drive-through and walk-up sales, but the proposal has not become a new retail permission. The city’s record for Ordinance 2026-407 shows the November 10 City Life Committee item was continued, with December 8 listed as its next meeting date.

The proposal introduced by Mayor Keith Wilson combines two subjects: updating the language governing exterior sales windows and revising the way licensing-payment provisions appear in city code. For cannabis shoppers, the first is about how a purchase might be collected. For operators, the second concerns the timing and administration of license costs.

A retailer considering a physical alteration would still need to assess the property and any other applicable approvals. Removing one cannabis-specific sales restriction is not the same thing as approving a building project.

The window restriction is specific

Portland’s current marijuana licensing chapter bars sales from vendor carts, temporary structures, satellite locations and exterior openings such as drive-through facilities or walk-up windows. The proposed amendment would remove the exterior-opening language while retaining restrictions on those other kinds of sales locations.

That is narrower than allowing cannabis sales anywhere a customer can drive or walk. A licensed premises would still be a particular business location, subject to the rest of its applicable requirements. The change concerns a method of serving customers, not the disappearance of the licensing system.

City materials say the amendment would align Portland’s wording with Oregon rules that made on-site delivery a permanent option in September 2020, following temporary pandemic arrangements. That history helps explain why the debate is framed as an update to conflicting language rather than a brand-new statewide retail model.

Convenience does not mean on-site consumption

One important boundary remains in the proposed code exhibit: the provision against consumption on licensed premises is retained, with its existing narrow employee exception under Oregon law. A pickup window and a consumption lounge are different activities.

The same exhibit retains operating-hour and security requirements. Its redline shows a targeted deletion concerning sales openings, rather than an across-the-board removal of the rules governing retail premises. Reading the actual proposed changes is more informative than assuming that the phrase drive-through implies a completely different type of store.

For a customer, the practical questions would still include whether a specific retailer offers a service, how the order is handled and which rules apply. A citywide code amendment, if adopted, would not guarantee that every shop installs a window or changes its property layout.

The payment provisions affect operators differently

The ordinance also addresses the Deferred Payment Program for license fees. The city’s explanation says a 50% initial payment better supports collection and that the code should refer to the council-approved fee schedule rather than preserve outdated dollar amounts.

That is a distinction between the text of the code and the administration of a program. City materials say programmatic changes were communicated in June and July and implementation began in August. The proposal would codify practices already in place, according to the city, rather than introduce every payment change for the first time.

Operators evaluating the proposal therefore need both the amended text and the applicable fee schedule. A headline about pickup windows does not explain a business’s entire licensing bill, and an old fixed amount quoted from code may not describe current program administration.

Businesses are raising questions about cash flow

In KPTV’s November 10 reporting, Mikhala Armstrong described support for greater accessibility alongside concerns from cannabis operators about payment obligations and late fees. Those interviews add an important perspective to the city’s stated goal of improving administration.

The two views are not interchangeable. The city describes its intended program effects; individual operators describe how they believe the arrangements affect their businesses. A final assessment should distinguish those accounts from evidence about what happens after implementation.

Our coverage of Missouri’s interstate cannabis guidance concerned a separate jurisdiction, but illustrates a related point: legal cannabis markets remain governed by specific rules at different levels. A state allowance does not make every local detail irrelevant.

The next step is still a public decision

The city’s document history is the place to follow whether the committee advances or amends the proposal. As of this review, its status is continued, not adopted. Readers should check the updated agenda before relying on the December meeting listing or making plans to offer a new service.

The potential change is concrete: remove a particular restriction on how licensed cannabis stores serve customers and bring fee language into line with current administration. Whether that becomes the final city policy remains the question before Portland, rather than a decision already made.

Illustrative Portland waterfront photograph; not a dispensary or proposed pickup site. Photo: Meggyn Pomerleau / Unsplash.

Continue Reading

Trending

Join The Cannabis Aficionado Community!
Join the Cannabis Aficionado community and receive all of the most relevant news geared towards our sophisticated enthusiast community.
Loading

Copyright ©️ 2026 Cannabis Aficionado. Cannabis Aficionado is a registered trademark of CNM Inc. All rights reserved. Registration on or use of this site constitutes acceptance of our Terms of Service, Privacy Policy and Cookies Policy. People may receive compensation for some links to products and services. Offers may be subject to change without notice.